
Muara is a two-sided lending market for tokenized stocks. Long holders unlock cash without selling, short sellers get real stock supply, and each side's collateral protects the other.
Tokenized US stocks are already sold to Indonesian retail users through local exchanges, and OJK is drafting rules for tokenized asset offerings. Yet these tokens are financially inert once bought. Three gaps follow:
1. Holders cannot unlock liquidity. The only way to access the cash value of a tokenized stock is to sell it, which forfeits upside and triggers a taxable exit.
2. There is no way to express a bearish view. No stock supply exists for short sellers, so price discovery on tokenized equities is one-directional. For Indonesian stocks the gap is structural: retail short selling on the IDX is effectively unavailable, so the local market has never had a two-sided mechanism.
3. Capital sits idle. Collateral in existing lending markets earns nothing while it secures a loan, and tokenized stocks are not accepted as collateral at all.
Existing DeFi lending protocols are built for crypto assets. They ignore market hours, so a token that trades 24/7 against an underlying that is closed can be liquidated on a stale price. They also offer no way for a holder to opt out of having their shares lent, which matters for sharia-compliant users.
Muara is a two-sided lending market for tokenized stocks where each side's collateral protects the other.
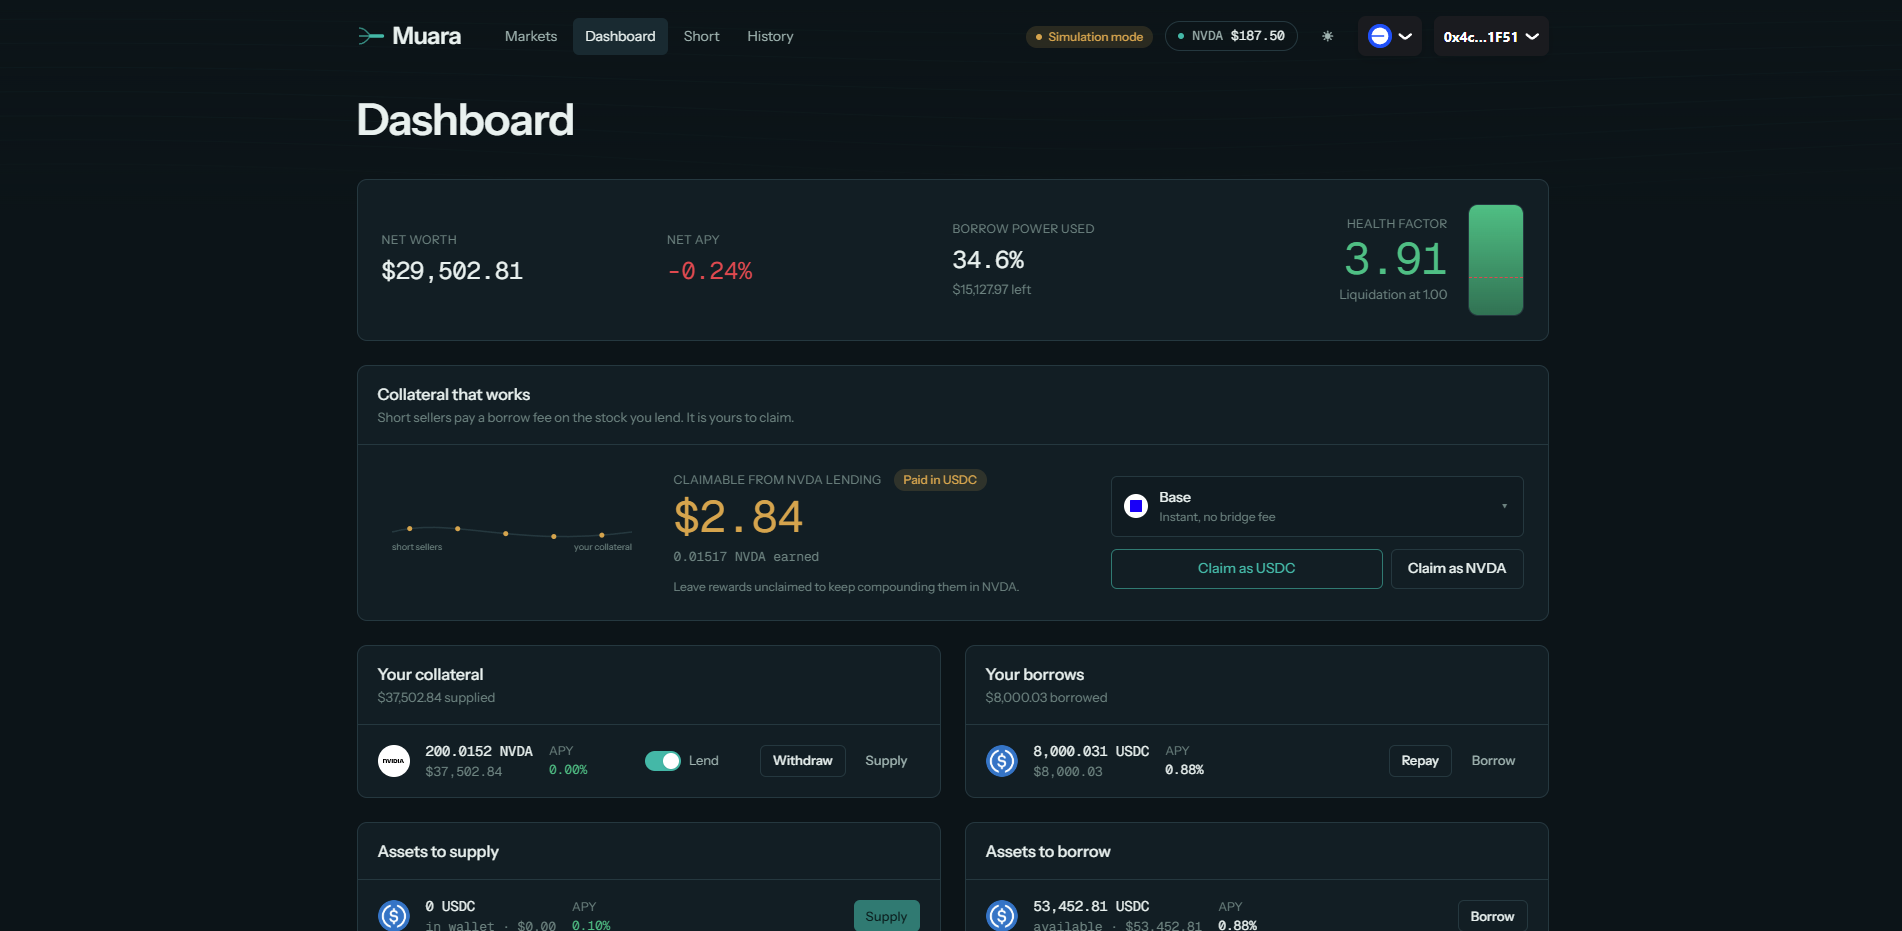
- Long holders lock stock tokens and borrow USDC against them. Their locked stock is lent to short sellers, and the borrow fee they earn offsets their own interest cost. Collateral works instead of sitting idle. Yield is paid in USDC on claim.
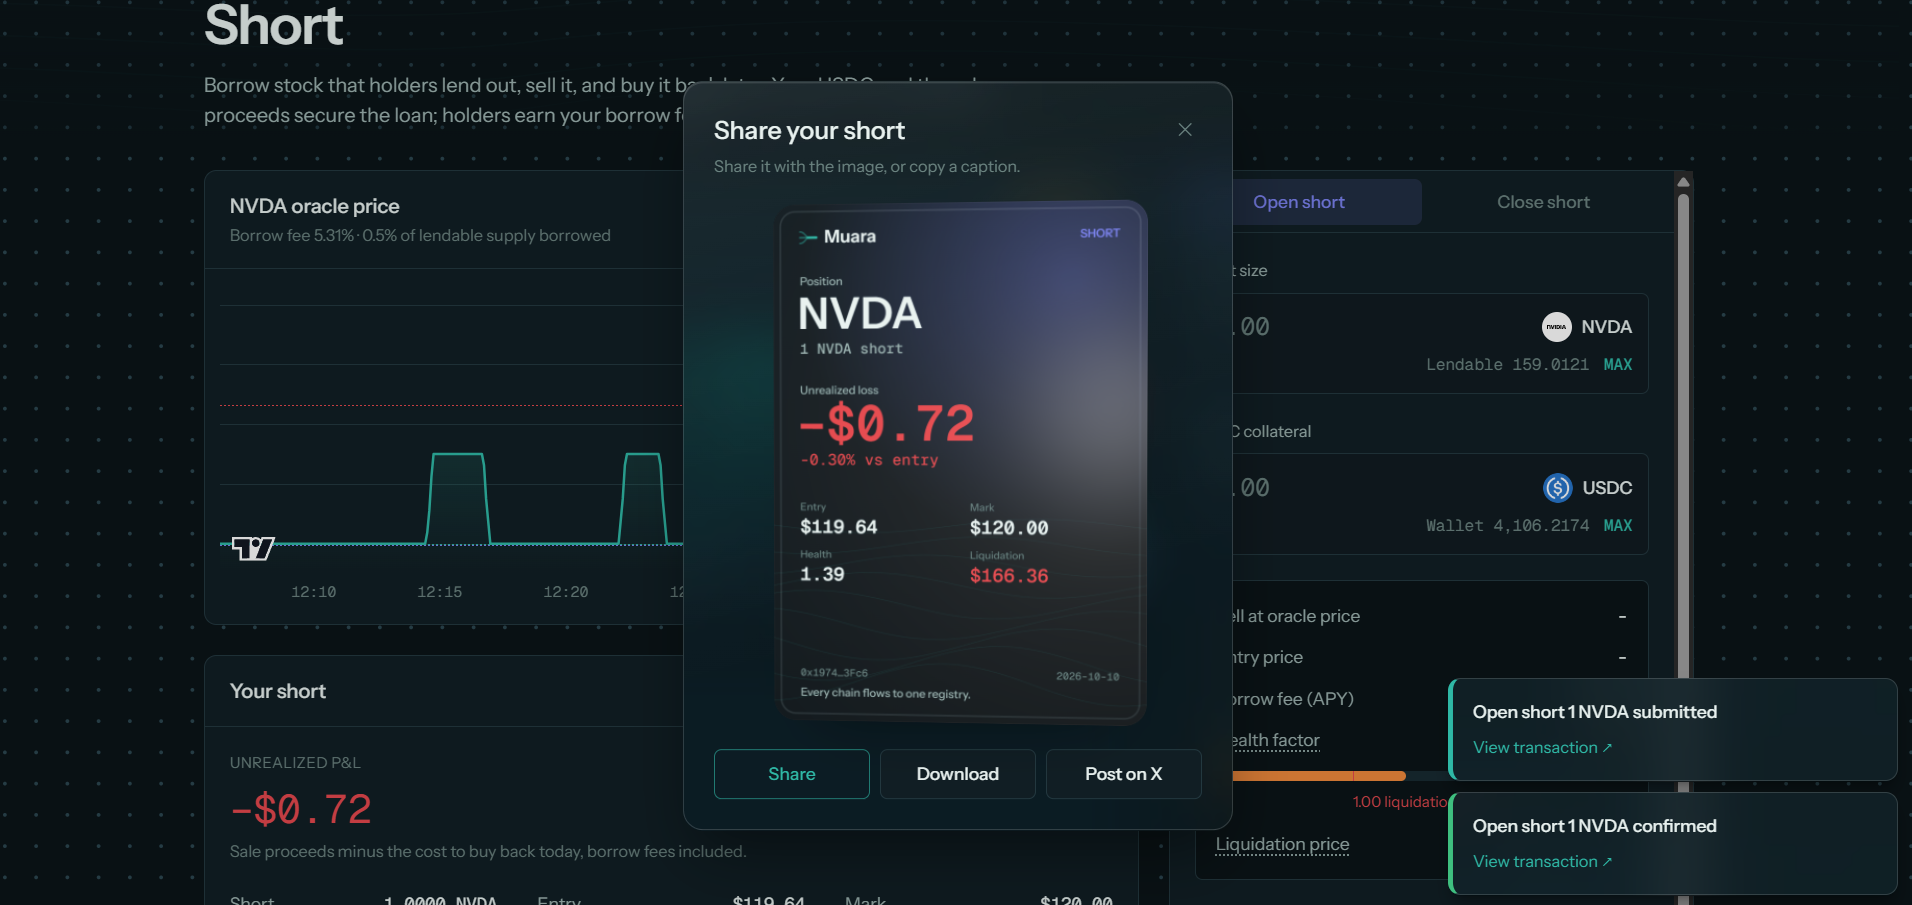
- Short sellers lock USDC and borrow stock tokens, which they sell at market and buy back later. Opening and closing a short is a single transaction through an integrated exchange.
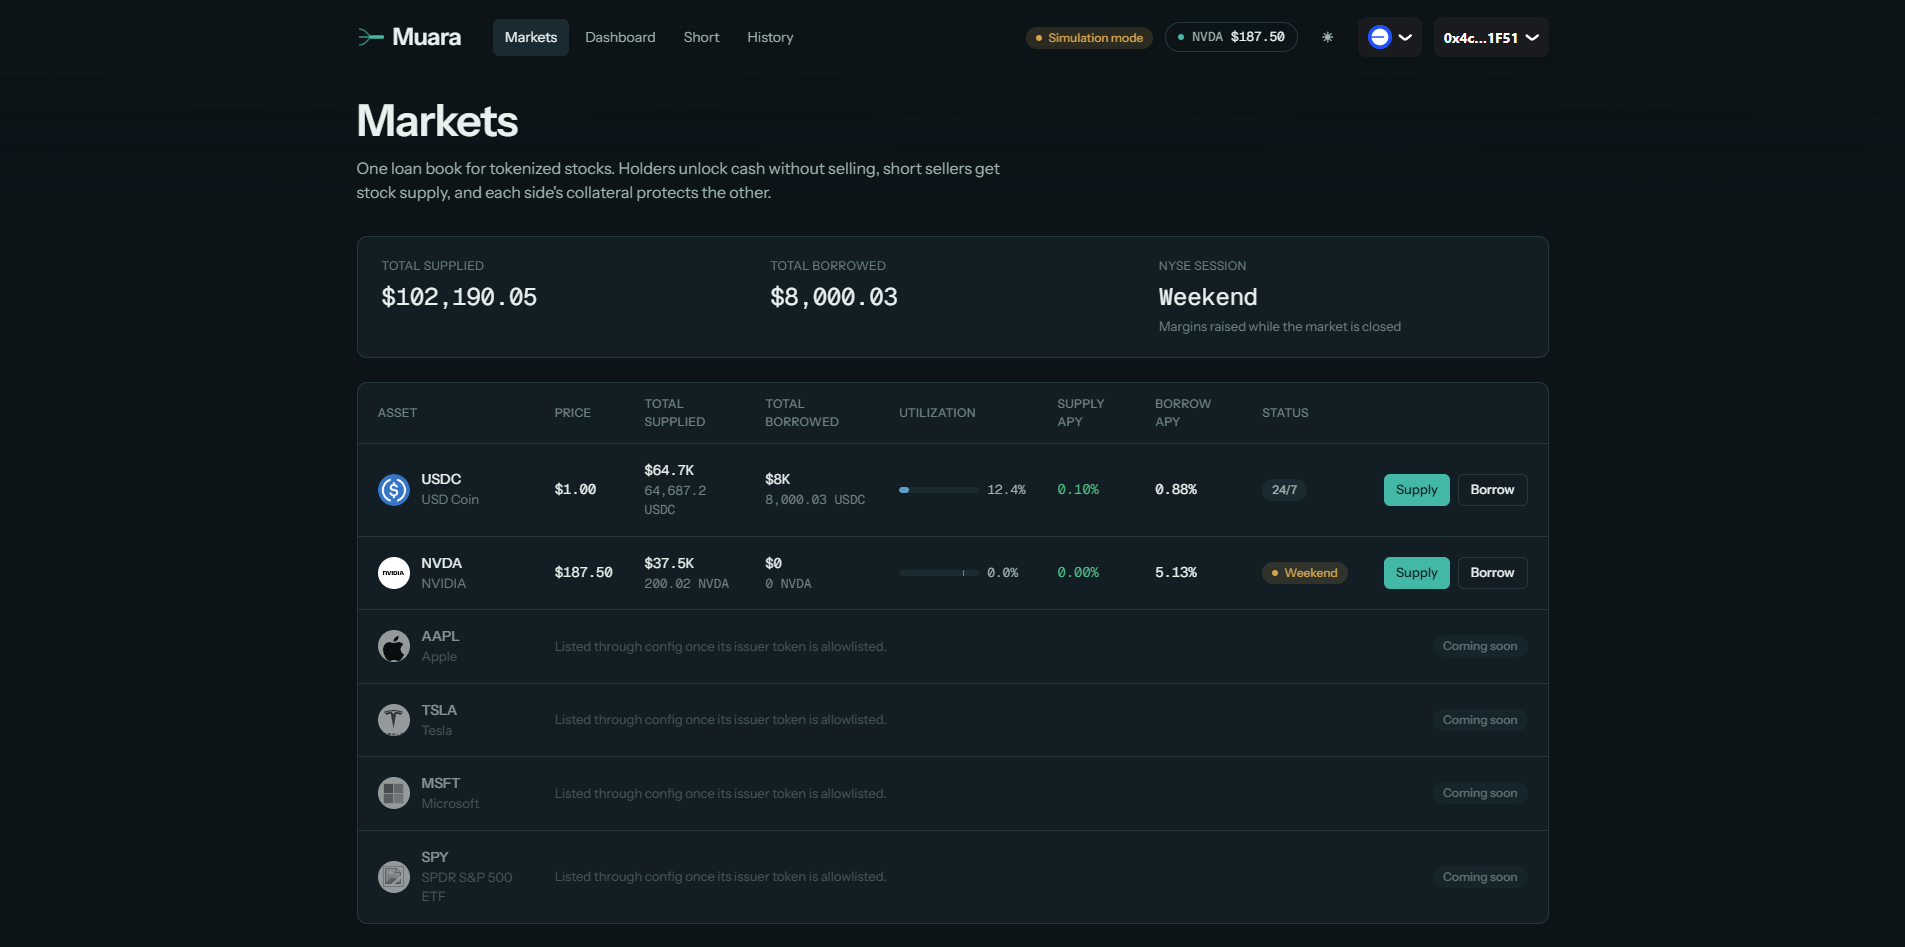
- USDC suppliers fill liquidity gaps and earn interest.
Risk is managed per asset with overcollateralization (150% initial, 120% maintenance for NVDA) and a market-hours-aware risk engine that raises margin requirements before closes and weekends and pauses liquidations when prices are stale. Liquidation is permissionless and executed by a keeper bot. Owners can mark holdings as not lendable to satisfy sharia requirements.
Cross-chain delivery runs on LayerZero. All lending logic and the single loan book live on Base, while users can receive borrowed USDC or withdraw collateral on Arbitrum. Stock tokens and USDC are native OFTs, and the stock token enforces its transfer allowlist on every chain. Health factor is checked on the hub before any cross-chain delivery.
Every leg of a Muara position settles in stablecoins, never in rupiah. OJK's restriction applies to fiat-to-crypto rails, not to stablecoin-to-token activity, so the market structure Muara provides sits inside the permitted perimeter. When tokenized IDX stocks launch, they plug into Muara through configuration alone, and Indonesian investors gain for the first time a compliant way to short domestic equities, hedge a portfolio, and earn yield on holdings they would otherwise leave idle. Sharia opt-out is built in from day one so the same market serves both conventional and sharia-compliant investors.
NVDA is live today. AAPL, TSLA, MSFT and SPY are staged, and IDX tokens follow the same path once issued.
Implemented Layer Zero for Cross Chain, Base for the main Contract.
Nope
